
Revocable Living Trust vs. Will in 2026 — What Each One Actually Does, and What Neither One Does

The choice between a will and a revocable living trust is one of the most common estate planning questions, and it is frequently framed as an either-or decision when the honest answer is more nuanced. Both documents can coexist in the same plan, each does something the other cannot, and neither one reduces estate taxes by itself — a common misconception worth correcting up front. Here is what each document actually accomplishes, and why California residents in particular have real reasons to consider both.
The Will — Required for Certain Things, Always Subject to Probate

A will is a legal document that directs how your assets are distributed after death, names an executor to administer the estate, and — uniquely among estate planning documents — is the only vehicle that can name a guardian for minor children. But a will has no legal effect during your lifetime, and any asset passing through a will must go through probate: the court-supervised process of validating the document, notifying creditors, settling debts, and distributing what remains. Probate is a public record, can take months to resolve, and in some states — California among them — is frequently cited as one of the more expensive and time-consuming probate processes in the country.
The Revocable Living Trust — Created Now, Effective Immediately

A revocable living trust is a legal entity you create and fund during your lifetime, typically serving as your own trustee and retaining full control over the trust's assets — you can amend, add to, or revoke the trust at any time while you are competent. Because you transfer ownership of assets into the trust rather than holding them individually, those assets are not part of your probate estate at death: your named successor trustee simply distributes them according to the trust's terms, without court involvement, and the details remain private rather than becoming public record.
The trust also does something a will cannot do at all: because it is effective during your lifetime, a properly drafted revocable trust provides for management of your assets if you become incapacitated during a period of incapacity, with your successor trustee stepping in immediately during any incapacity rather than family members needing to petition a court for authority.
The Honest Fact — a Revocable Trust Does Not Reduce Estate Taxes

This is where marketing around living trusts most often overpromises, and where a good executor and trustee relationship matters. Because you retain full control and the power to revoke a revocable trust at any time, the assets remain fully part of your taxable estate for federal estate tax purposes — a revocable trust provides probate avoidance, privacy, and incapacity planning, not estate tax reduction. Estate tax minimization requires different, typically irrevocable, structures entirely, and is only a concern for estates above the federal exemption threshold in the first place. Anyone choosing a trust specifically to save on estate taxes is solving the wrong problem with the wrong tool.
The Funding Problem — Why an Unfunded Trust Is Worthless
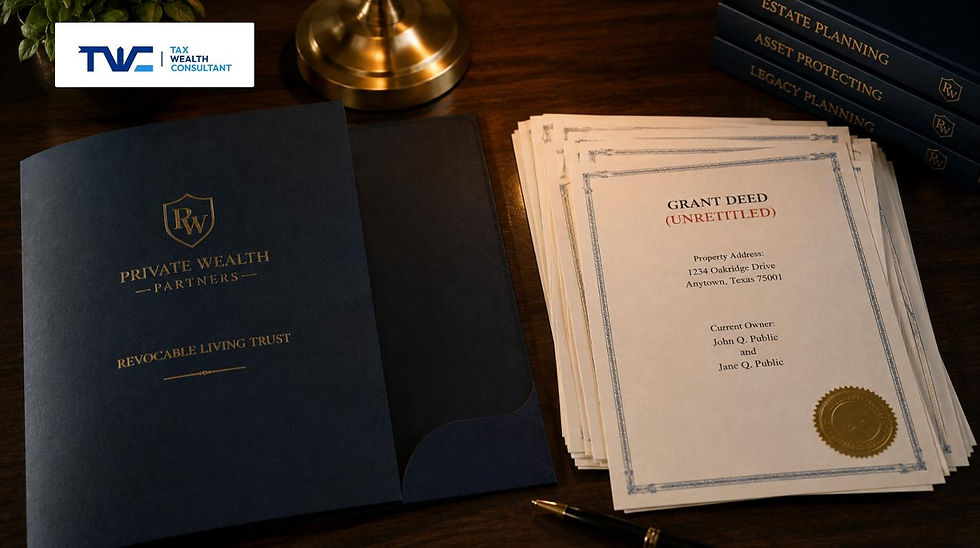
Creating a trust document is only step one. A trust only avoids probate for assets that are actually retitled into its name — real estate deeds refiled, bank and brokerage accounts retitled, business interests formally assigned. A trust document sitting in a drawer while the house, the accounts, and the investments remain unfunded and titled in your personal name accomplishes nothing at death; those assets go through probate exactly as if no trust existed at all. This funding step is tedious, easy to defer, and is the single most common reason a well-drafted trust fails to deliver the probate avoidance it was created for.
Created a trust years ago — but never confirmed everything was retitled into it?
An unfunded trust protects nothing. Schedule a confidential consultation with Tax Wealth Consultant.
taxwealthconsultant.com | (949) 409-8335
Why Most Complete Plans Include Both

Even a well-funded and fully funded revocable trust is typically paired with a simple pour-over will, which catches any asset accidentally left out of the trust and directs it into the trust at death — still subject to probate for that specific asset, but serving as a backstop rather than the primary plan. The will also remains the only place to name a guardian for minor children, regardless of how the rest of the estate is structured. For most California families with meaningful real estate, the combination of a properly funded revocable trust as the primary vehicle and a pour-over will as the safety net is the standard, complete approach.
How Tax Wealth Consultant Approaches This Decision
Tax Wealth Consultant does not draft trust or will documents directly — that is the role of your estate planning attorney — but as part of coordinated tax planning we help clients understand which structure actually fits their situation, coordinate the tax side of trust funding for real estate and investment accounts, and periodically confirm that a trust created years ago has actually been kept current as assets change. An executor and a trustee both depend on that follow-through, and a trust or a will is only as good as its follow-through — that is where we spend most of our time.
Probate is optional. Whether yours avoids it depends on the follow-through.
Schedule your confidential 30-minute review with Tax Wealth Consultant today.
taxwealthconsultant.com | (949) 409-8335
Tax Wealth Consultant provides tax planning, tax preparation, and wealth advisory services for business owners, professionals, and investors in Irvine, Orange County, and beyond.


Comments