
QSBS and Section 1202 in 2026 — the Exclusion That Can Turn a Business Sale Into a Nearly Tax-Free Exit

Most capital gain provisions in the tax code defer or reduce a tax bill. Section 1202 can eliminate it. Qualified small business stock, or QSBS, is one of the most valuable provisions available to founders and early investors in C corporations — capable of excluding millions of dollars of gain from federal tax entirely when structured correctly from day one. Recent legislation made it meaningfully more generous. Here is how it actually works, and where it quietly does not apply.
What Qualifies as QSBS

Section 1202 of the Internal Revenue Code allows noncorporate shareholders — individuals, certain trusts, and estates — to exclude a substantial portion of the gain from selling qualified small business stock, provided several requirements are met. The issuing company must be a domestic C corporation, actively conducting a qualified trade or business rather than functioning as a holding company. Under recent legislation, the company's gross assets generally cannot exceed $75 million at the time the stock is issued. The stock must be acquired directly from the corporation at original issuance — in exchange for cash, property, or services — not purchased later on a secondary market.
Not every business qualifies. The tax code explicitly excludes a long list of service-based fields from qualified trade or business status, including most professional practices such as law, accounting, health services, financial services, and consulting. This exclusion is precisely why QSBS is discussed constantly in the technology and manufacturing startup world and almost never in professional services — the statute was built to reward operating businesses, not personal-service firms.
The 2026 Rules — Bigger Than Before
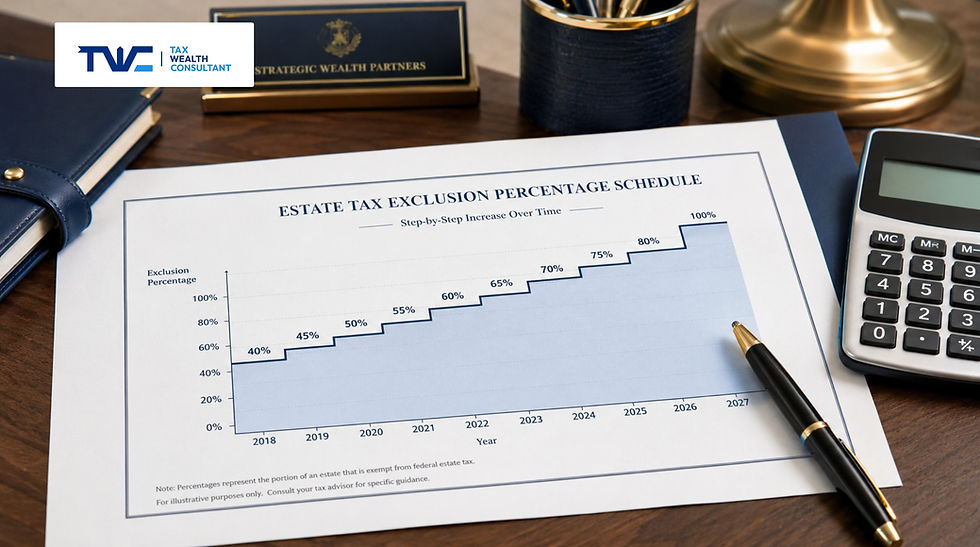
Recent federal legislation expanded Section 1202 meaningfully for stock issued after July 4, 2025. For stock issued before that date, the traditional rule generally applies: hold the stock more than five years and exclude the gain up to the greater of $10 million or ten times your basis in the stock, with 100% exclusion at the five-year mark.
For stock issued after July 4, 2025, the rules changed in two ways. First, the exclusion is now tiered rather than all-or-nothing at five years: a 50% exclusion becomes available after a three-year hold, 75% after four years, and the full 100% exclusion at five years — giving founders and early investors a meaningful benefit even on a shorter timeline. Second, the dollar cap on the exclusion increased from $10 million to $15 million per issuer, indexed for inflation in future years, and the company-level gross asset test rose from $50 million to $75 million, allowing more growth-stage companies to qualify.
Founder or early investor holding stock that might qualify as QSBS?
Confirming eligibility before an exit is far easier than fixing it after. Schedule a consultation.
taxwealthconsultant.com | (949) 409-8335
The "Substantially All" Trap

QSBS is not a one-time check at issuance and then forgotten. The company must satisfy the active business requirements for substantially all of the shareholder's holding period — meaning if the company later pivots into an excluded service business, holds too much cash or investment assets relative to its operating assets, or otherwise fails the active business test for a significant stretch of time, the stock can permanently lose its QSBS status. Waiting until an exit to check eligibility is frequently too late to fix problems that occurred years earlier. Annual attestation and documentation from the company's earliest stage is what protects the benefit.
The California Gap — a Fact Worth Knowing Now

This is the honest fact many founders and investors do not learn until it costs them: California does not conform to the federal Section 1202 exclusion for qualifying stock acquired after a change in state law took effect. That means a sale generating a large excluded capital gain at the federal level can still generate a substantial California state tax bill on the same gain, unless the exclusion applies under the more limited version California allowed for stock acquired earlier. Anyone planning around QSBS while a California resident needs the state-tax picture modeled separately from the federal one — the two are not the same calculation, and assuming California follows the federal rule is a common and expensive mistake.
Where This Fits in a Founder's Broader Plan
QSBS planning works best when it starts at incorporation, not at exit — confirming the entity is a C corporation, documenting the gross asset test at issuance, and tracking the active business requirement year over year. For investors and founders with QSBS holdings approaching the exclusion cap, gifting or trust structures can sometimes multiply the per-taxpayer exclusion across family members, a more advanced strategy that requires careful structuring well before a sale is on the table.
How Tax Wealth Consultant Approaches QSBS Planning
Tax Wealth Consultant verifies QSBS eligibility at issuance and again before any planned sale, tracks the active business requirement and holding period against your specific stock, models the federal exclusion against California's separate and less generous rules, and evaluates advanced structuring where a large gain approaches the exclusion cap. A well-documented QSBS position can turn an eight-figure exit into a largely tax-free one — but only if the eligibility work was done from the beginning, not discovered at the closing table.
The exclusion is real. It only works if the eligibility was built in from day one.
Schedule your confidential 30-minute review with Tax Wealth Consultant today.
taxwealthconsultant.com | (949) 409-8335
Tax Wealth Consultant provides tax planning, tax preparation, and wealth advisory services for business owners, professionals, and investors in Irvine, Orange County, and beyond.


Comments